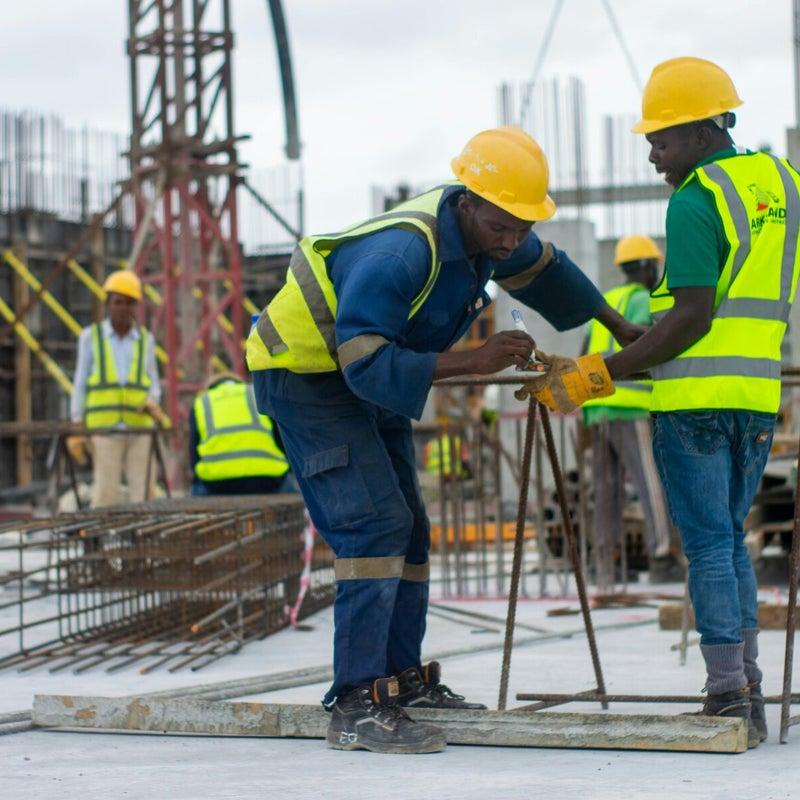
A workplace accident can happen in almost any business. A construction worker may fall while performing a task, a warehouse employee may suffer an injury while handling equipment, or an office worker may be injured during an activity connected to their employment. Beyond the immediate concern for the employee’s health, these incidents create important legal and administrative responsibilities for employers.
In Kenya, the Work Injury Benefits Act, 2007 (WIBA) provides a framework for compensation arising from qualifying work-related injuries and occupational diseases. Employers are expected to understand their responsibilities, maintain appropriate protection arrangements and follow the prescribed procedures when an incident occurs.
Yet WIBA is frequently misunderstood. Some business owners believe it applies only to factories and construction companies. Others assume that medical insurance or employee registration with statutory social protection programmes automatically fulfils their workplace injury obligations.
These assumptions can leave businesses exposed to compliance problems and employees uncertain about the protection available to them.
This guide explains what WIBA insurance means in Kenya, which employers and workers fall within its scope, the types of workplace incidents involved, reporting requirements, claims procedures and practical steps businesses can take to strengthen workplace risk management.
What Is WIBA Insurance in Kenya?
WIBA stands for the Work Injury Benefits Act, 2007. It is Kenyan legislation that establishes a framework for compensating employees who experience qualifying injuries or occupational diseases arising out of and in the course of their employment.
The legislation addresses the responsibilities of employers, the rights of eligible employees and dependants, reporting procedures, assessment of claims and the administration of work injury compensation.
WIBA insurance is commonly used to describe an insurance policy designed to address an employer’s liability under the Act.
Section 7 of the Act sets out the employer’s obligation to maintain appropriate insurance for liabilities arising under the legislation. Businesses should confirm their current statutory obligations and the suitability of their arrangements with a qualified adviser or relevant authority.
Importantly, WIBA is not simply an employee benefit offered at an employer’s discretion. It concerns responsibilities established under Kenyan law.
Who Administers WIBA in Kenya?
The Directorate of Occupational Safety and Health Services (DOSHS), under the State Department responsible for labour, plays a central role in workplace safety administration, accident investigations and WIBA processing.
DOSHS receives workplace accident notifications, undertakes relevant investigations and handles processes associated with work injury compensation under the applicable framework.
Employers can obtain official information through the Directorate of Occupational Safety and Health Services and the State Department for Labour and Skills Development.
Is WIBA Insurance Mandatory for Employers in Kenya?
The Work Injury Benefits Act establishes an obligation for employers to maintain insurance covering liability arising under the Act, subject to the applicable statutory framework.
This is an important compliance consideration for businesses employing workers in Kenya.
The legislation is not limited to businesses with large workforces or visibly hazardous operations. Employers should assess their responsibilities based on the nature of their employment relationships and the applicable legal definitions.
Does WIBA Apply to Small Businesses?
Yes. A business does not become exempt from work injury obligations simply because it operates on a small scale.
Small retailers, restaurants, cleaning companies, workshops, offices, hospitality businesses and other employers may have responsibilities under WIBA where they employ people covered by the Act.
For example, a small business with employees handling deliveries, cleaning premises or operating equipment may face workplace injury risks even when its activities appear relatively straightforward.
Does WIBA Apply to Office-Based Businesses?
Office environments are generally less associated with heavy machinery or construction hazards, but workplace injuries can still occur.
Employees may experience slips, falls or other accidents connected to their duties. Certain occupational health conditions may also require assessment where they are alleged to arise from employment.
Businesses providing accounting, consultancy, administrative, technology or other office-based services should therefore not assume that workplace injury obligations are irrelevant.
Which Employees Are Covered Under WIBA in Kenya?
WIBA applies to employees falling within the definitions and scope established by the Act. The statutory framework covers a broad range of employment relationships, subject to its specific provisions and exclusions.
Employers should review the status of the people working for their organisations rather than assume that only permanent employees are relevant.
Permanent Employees
Employees working under continuing employment arrangements are a central category when assessing workplace injury responsibilities.
Employers should maintain accurate employee information and ensure that relevant work activities are reflected in their protection arrangements.
Temporary and Casual Workers
Businesses frequently engage temporary or casual workers during busy periods, seasonal operations or short-term projects.
Such arrangements should not automatically be treated as outside WIBA. Whether a particular worker qualifies as an employee depends on the applicable legal definitions and the facts of the working relationship.
Domestic Workers
Households employing domestic workers, including housekeepers, drivers and other household staff, should consider their responsibilities under the Act.
Workplace injury protection is not relevant only to commercial premises. Employment activities performed in domestic settings can also involve injury risks.
Contractors and Subcontractors
Construction companies, property managers, manufacturers and other businesses may work with contractors and subcontractors.
These arrangements require particular attention because responsibility may depend on the actual employment relationship, contractual arrangements and statutory provisions.
A business should not assume that a contractor’s presence automatically transfers every workplace injury obligation away from the principal business.
For complex contractor arrangements, obtain appropriate legal and insurance guidance.
What Does WIBA Insurance Cover in Kenya?
WIBA concerns qualifying employment-related injuries, occupational diseases and resulting consequences defined by the Act.
The precise benefits available under an insurance policy must be reviewed alongside the statutory framework, the insurer’s policy wording and the circumstances of the claim.
1. Work-Related Accidental Injuries
Employees may sustain injuries while performing their assigned duties, operating equipment, moving materials or carrying out other employment-related activities.
Where an incident meets the applicable requirements, it may fall within the WIBA compensation framework.
2. Temporary Disablement
Some workplace injuries prevent an employee from performing their normal duties for a period while they recover.
The Act contains provisions concerning temporary disablement, including the conditions under which an eligible employee may receive compensation.
The relevant assessment depends on the nature of the injury, medical evidence and applicable legal requirements.
3. Permanent Disablement
A serious workplace accident may result in a lasting physical impairment or loss of function.
WIBA contains provisions for assessing permanent disablement. The nature and degree of disablement are relevant to the determination of statutory benefits.
Medical assessment and the applicable legal framework are important in this process.
4. Fatal Workplace Accidents
Where a qualifying work-related accident results in an employee’s death, the Act provides for compensation involving eligible dependants.
The employer must also comply with the applicable notification and reporting requirements for fatal accidents.
5. Occupational Diseases
Not every work-related health condition results from a single sudden accident.
Some occupational diseases develop through exposure to workplace hazards over time. Depending on the circumstances and applicable legal requirements, these may fall within the WIBA framework.
Examples of occupational risks can include exposure to harmful substances, certain types of dust, excessive noise or other workplace hazards.
Whether a particular condition qualifies requires assessment under the relevant statutory provisions and medical evidence.
6. Medical Assistance Associated With Qualifying Injuries
The Act includes provisions addressing medical assistance and related employer responsibilities following qualifying workplace injuries.
Employers should understand the applicable requirements concerning treatment, documentation and cooperation with the claims process.
WIBA Coverage at a Glance
| Workplace Event | Potential WIBA Relevance | Important Consideration |
|---|---|---|
| Employee injured while performing assigned duties | May qualify as a work-related accident | Employment connection and accident circumstances |
| Temporary inability to work after an injury | May qualify for temporary disablement provisions | Medical assessment and statutory requirements |
| Permanent impairment following an accident | May qualify for permanent disablement provisions | Degree of disablement and supporting evidence |
| Fatal accident arising from employment | May give rise to dependant compensation | Eligibility and fatal accident reporting |
| Occupational disease linked to workplace exposure | May qualify under occupational disease provisions | Diagnosis, exposure history and legal requirements |
| Injury unrelated to employment | Generally outside ordinary WIBA scope | Actual circumstances and applicable exceptions |
This table is a general guide. The outcome of any claim depends on the facts, applicable law and relevant policy conditions.
WIBA Insurance Requirements for Employers in Kenya
Employers should treat WIBA compliance as part of their overall employment and workplace safety responsibilities.
Obtaining an insurance policy is an important consideration, but effective compliance also requires accurate records, appropriate reporting procedures and cooperation when workplace incidents occur.
Maintain Appropriate Work Injury Protection
Review whether the business has an appropriate and valid arrangement addressing its obligations under the Act.
Ensure that the insurer understands the nature of the business, the activities employees perform and any relevant occupational risks.
Maintain Accurate Employee Records
Businesses should keep relevant employment information, including employee details, duties, earnings records and other information required under applicable law.
Accurate records support employment administration and may become important during workplace injury investigations and compensation assessments.
Establish Workplace Accident Reporting Procedures
Employees and supervisors should know whom to notify when an incident occurs.
The business should also have a process for recording relevant facts, obtaining medical assistance and making the required notifications to the appropriate authority.
Cooperate With Investigations
Where DOSHS investigates an incident, the employer should cooperate with lawful requests for information and relevant records.
Incident reports, witness accounts and medical documentation may help establish the circumstances of an injury.
Review Occupational Safety Measures
Insurance does not replace the obligation to maintain a safe working environment.
Employers should identify workplace hazards, implement appropriate controls, provide relevant safety training and review their procedures as operations change.
How to Report a Workplace Accident Under WIBA in Kenya
Accident reporting is one of the most important responsibilities an employer should understand.
According to official DOSHS guidance, fatal workplace accidents should be reported within 24 hours, while non-fatal occupational accidents should be reported within seven days using the prescribed procedures.
The Work Injury Benefits Act also sets out requirements for reporting accidents after the employer receives notice or learns of the injury.
Step 1 — Provide Immediate Assistance
Prioritise the injured person’s safety and obtain appropriate medical attention.
Where necessary, stop the activity or isolate the hazard to prevent further injuries.
Step 2 — Notify the Responsible Employer Representative
The employee or person witnessing the incident should notify the appropriate supervisor, manager or employer representative as soon as practicable.
The employer should record when and how the incident was reported.
Step 3 — Record the Incident
Document the location, date, time, activity being performed, nature of the injury and available witness information.
Preserve relevant evidence and avoid making unsupported assumptions about the cause.
Step 4 — Report to DOSHS
Follow the applicable statutory notification requirements and submit the prescribed accident report.
DOSHS identifies the DOSHS 1 form as the relevant accident reporting form.
Fatal incidents require particular urgency. Employers should ensure the immediate notification and subsequent written reporting requirements are followed.
Step 5 — Notify the Insurer
Where the employer has relevant WIBA insurance, notify the insurer according to the policy’s claims conditions.
Reporting an accident to an insurer does not automatically replace statutory reporting to DOSHS.
Step 6 — Cooperate With the Claims Process
Provide the requested documents, respond to relevant inquiries and maintain communication with the employee or eligible dependants.
Keep copies of reports and correspondence for future reference.
Important WIBA Reporting Timelines in Kenya
| Event | Reporting Requirement | Responsible Party |
|---|---|---|
| Fatal workplace accident | Notify the relevant authority within 24 hours and follow the prescribed written reporting requirements | Employer |
| Non-fatal workplace accident | Report within seven days under the applicable statutory procedure | Employer |
| Occupational disease | Employer to report within fourteen days after receiving notice or learning of the disease under WIBA | Employer |
| Claims information received by employer | Forward relevant documents within the statutory period applicable under section 24 | Employer |
Employers should consult the current legislation and DOSHS instructions for the precise timing, method and documentation required in each case.
What Is the DOSHS 1 Form in Kenya?
The DOSHS 1 form is the prescribed form used in reporting occupational accidents to the Directorate of Occupational Safety and Health Services.
It helps capture relevant information about the incident and supports the administrative and investigation process.
Information Commonly Relevant to Accident Reporting
- Employer and workplace identification details.
- Information identifying the injured employee.
- Date and location of the accident.
- Nature of the work being performed.
- Description of how the incident occurred.
- Details of the reported injury.
- Relevant witness or supervisor information.
- Other particulars required by the prescribed form.
Employers should use the current prescribed form and follow the instructions provided by DOSHS rather than relying on outdated documents.
How Does the WIBA Claims Process Work?
The WIBA claims process involves reporting the incident, gathering relevant evidence and assessing whether the circumstances satisfy the applicable legal requirements.
Different claims may require different forms of evidence depending on whether the case involves temporary disablement, permanent disablement, occupational disease or death.
Accident Notification
The process begins with appropriate notification of the incident and submission of the required reports.
Medical Documentation
Medical records help establish the nature of the injury, treatment received and any relevant disability assessment.
For occupational diseases, medical diagnosis and information concerning workplace exposure may be particularly important.
Investigation and Assessment
DOSHS may undertake inquiries or investigations relevant to the claim.
The circumstances of the incident and applicable statutory provisions are considered in determining the appropriate outcome.
Determination of Benefits
Where a claim qualifies, the relevant benefits are determined according to the applicable legal framework and the facts established.
The involvement of an insurer does not eliminate the need to comply with the statutory claims process.
Claim Completion and Records
Employers should retain the relevant claim documentation, official correspondence and records of the process.
Official DOSHS guidance refers to a WIBA 7 certificate in the completion of relevant compensation processes.
What Documents May Be Needed for a WIBA Claim?
The exact documents depend on the incident and the requirements of the relevant authority or insurer.
Commonly relevant records may include:
- Completed prescribed accident notification forms.
- Employee identification and employment information.
- Relevant employment and earnings records.
- Medical reports and supporting clinical documentation.
- Incident reports and witness statements.
- Accident investigation findings where available.
- Relevant insurer claim forms.
- Death-related and dependant documentation in fatal cases.
- Additional records requested through the lawful claims process.
Employers should handle employee medical and personal information carefully and share it only through appropriate authorised channels.
WIBA Insurance vs Employer’s Liability Insurance in Kenya
WIBA insurance and employer’s liability insurance are related to workplace risks, but they are not necessarily interchangeable.
WIBA addresses statutory compensation obligations associated with qualifying employment-related injuries and occupational diseases.
Employer’s liability insurance generally concerns specified legal liabilities arising from employee injury or illness claims, subject to the terms of the particular policy.
The relationship between these covers depends on Kenyan law, the wording of the insurance contracts and the circumstances of a claim.
| Feature | WIBA Insurance | Employer’s Liability Insurance |
|---|---|---|
| Main purpose | Addresses liabilities arising under the Work Injury Benefits Act | Addresses specified employer legal liabilities under the policy |
| Legal foundation | Statutory work injury compensation framework | Relevant legal liability and contractual coverage |
| Typical concern | Qualifying workplace injuries and occupational diseases | Specified employee injury or illness liability claims |
| Claims assessment | Applicable WIBA provisions and procedures | Relevant law and insurance contract terms |
| Are they identical? | No | No |
Businesses should seek advice about whether additional employer’s liability protection is appropriate for their activities.
Explore Mnara’s Business and Corporate Insurance services for guidance on WIBA, employer’s liability and related workplace protection.
WIBA Insurance vs Group Personal Accident Insurance
Group personal accident insurance may provide specified benefits to covered individuals following qualifying accidental events.
Some policies offer protection for events occurring both during and outside working hours, depending on the selected terms.
WIBA, however, concerns statutory responsibilities relating to qualifying work-related injuries and occupational diseases.
Employers should not assume that a group personal accident policy automatically fulfils all obligations under WIBA.
Why Businesses May Consider Both
An employer may wish to address statutory workplace injury responsibilities while also considering additional accident-related employee benefits.
The suitability of such arrangements depends on the organisation’s workforce, existing benefits and applicable policy conditions.
WIBA Insurance for Construction Companies in Kenya
Construction activities often involve elevated workplace risks because employees may work at height, handle heavy materials, operate machinery or perform tasks in changing site conditions.
Construction employers should assess work injury responsibilities carefully and maintain appropriate safety procedures.
Common Construction Workplace Hazards
- Falls from elevated working areas.
- Injuries involving tools and equipment.
- Accidents during material handling.
- Incidents involving moving machinery.
- Electrical hazards.
- Exposure to dust and other occupational hazards.
Construction businesses should also review subcontractor arrangements, employee records, incident reporting procedures and relevant safety requirements.
WIBA protection should form part of a wider risk management approach rather than being treated as a substitute for accident prevention.
WIBA Insurance for Factories, Warehouses and Manufacturing Businesses
Manufacturing and warehousing environments may involve repetitive work, powered equipment, material handling, chemical exposure and other occupational risks.
Employers should assess these activities when reviewing workplace injury protection and safety controls.
Important Risk Management Measures
- Conducting relevant workplace risk assessments.
- Maintaining equipment and machinery appropriately.
- Providing task-specific safety training.
- Using suitable protective equipment where required.
- Maintaining incident reporting procedures.
- Reviewing occupational health risks.
- Keeping accurate employment and workplace records.
Where an occupational illness is suspected, employers should follow the applicable reporting and medical assessment requirements.
WIBA Insurance for Hotels, Restaurants and Hospitality Businesses
Hospitality businesses employ people in kitchens, housekeeping, maintenance, security, administration and guest services.
Each role may involve different workplace hazards.
For example, kitchen employees may face burns or cuts, housekeeping staff may encounter slips or lifting-related injuries, and maintenance employees may work with equipment or electrical systems.
Hospitality employers should review their work injury responsibilities across the entire workforce, not only employees performing obviously hazardous duties.
WIBA Insurance for Schools, Hospitals and Professional Offices
Educational institutions, healthcare facilities and professional offices also employ workers who may experience occupational injuries or health risks.
In schools, relevant activities may include maintenance, laboratory work, transport and general support services.
Healthcare employees may encounter particular occupational hazards depending on their duties and workplace environment.
Professional offices should consider ordinary workplace accidents and any occupational health risks relevant to their operations.
These organisations should not assume that the absence of industrial machinery means workplace injury compliance is unnecessary.
Does WIBA Cover Employees Working From Home?
Remote and hybrid working arrangements create important questions about the connection between an injury and employment.
An accident occurring at home is not automatically a work-related accident simply because the injured person is employed.
Equally, an employer should not automatically dismiss a reported injury merely because it occurred away from the main business premises.
The relevant question is whether the circumstances meet the legal requirements for an injury arising out of and in the course of employment.
Factors may include the employee’s assigned duties, the activity being performed and the circumstances surrounding the incident.
Employers with remote teams should establish clear incident reporting procedures and obtain appropriate advice where a claim raises complex questions.
Does WIBA Cover Employees Travelling for Work?
Work-related travel can raise questions about whether an accident occurred in the course of employment.
Under WIBA, the circumstances of travel matter. The Act contains provisions relevant to transport connected with employment, including certain employer-provided transport arrangements.
However, not every journey between home and work is automatically covered.
Employers should review the specific facts and applicable legal provisions rather than apply a blanket assumption to every transport incident.
What Happens If an Employer Does Not Have Appropriate WIBA Protection?
Failure to meet statutory work injury obligations can expose an employer to legal and operational difficulties.
An employer may still face responsibilities arising under the Act even where appropriate insurance arrangements were not maintained.
Depending on the circumstances, non-compliance may also result in regulatory consequences.
For a business, a serious workplace incident can disrupt operations, affect employee confidence and require substantial management attention.
The appropriate response is to review compliance proactively rather than wait until an accident occurs.
Common Employer Compliance Mistakes
- Assuming WIBA applies only to high-risk industries.
- Failing to review the employment status of workers.
- Relying on ordinary medical insurance as a substitute for work injury protection.
- Failing to report accidents within the required periods.
- Keeping incomplete employee and incident records.
- Overlooking occupational disease reporting.
- Assuming contractors eliminate every employer responsibility.
- Failing to review protection when business operations change.
How to Strengthen WIBA Compliance in Your Business
A structured approach makes it easier to manage workplace injury responsibilities and respond appropriately when incidents occur.
1. Identify Your Workforce
Review the categories of people working for your business and identify employment relationships that require consideration under WIBA.
2. Assess Workplace Activities
Understand the duties employees perform, including work away from the main premises and activities involving occupational hazards.
3. Review Your Insurance Arrangements
Confirm that the business has suitable protection for its statutory responsibilities and that relevant information supplied to the insurer is accurate.
4. Maintain Proper Records
Keep employee information, incident records and other required documentation organised and accessible to authorised personnel.
5. Train Supervisors and Employees
Ensure workers know how to report incidents and supervisors understand the need for prompt action.
6. Establish a Claims Response Procedure
Document who is responsible for medical assistance, DOSHS reporting, insurer notification and communication with the affected employee.
7. Review Workplace Safety
Regularly identify hazards and evaluate whether existing controls remain appropriate.
8. Seek Professional Guidance
Where employment arrangements, insurance terms or workplace risks are complex, obtain advice from appropriately qualified professionals.
Employer WIBA Compliance Checklist
| Compliance Area | Action for Employers |
|---|---|
| Statutory obligations | Understand the applicable requirements under WIBA |
| Insurance arrangements | Review appropriate protection for statutory liabilities |
| Employee records | Maintain accurate employment and relevant earnings information |
| Workplace safety | Identify hazards and implement appropriate controls |
| Accident reporting | Follow DOSHS notification procedures and timelines |
| Occupational diseases | Report relevant cases under the applicable requirements |
| Claims documentation | Preserve reports, medical evidence and official correspondence |
| Staff awareness | Train employees and supervisors on incident reporting |
| Business changes | Review arrangements when operations or workforce conditions change |
How WIBA Fits Into a Wider Business Insurance Strategy
Work injury protection addresses an important category of employer risk, but businesses face other potential liabilities and operational threats.
A comprehensive risk review may also consider public liability, professional indemnity, group medical insurance, group life insurance, fire and burglary protection, and business interruption insurance.
Each of these products serves a different purpose.
For example, public liability insurance generally concerns specified third-party injury or property damage liabilities, while professional indemnity insurance concerns particular liabilities arising from professional services.
Business interruption insurance may address specified interruptions to business operations following insured events, subject to the relevant policy.
These protections should be evaluated according to the nature of the business rather than assumed to be interchangeable.
Explore Business and Corporate Insurance at Mnara Risk and Wealth Advisory to understand the different areas of business risk protection.
Why Employers Should Review WIBA When Their Business Grows
A business may begin with a small office team and later expand into warehousing, delivery operations, field services or multiple branches.
Such changes can alter the organisation’s workplace risk profile.
Hiring additional workers, introducing new equipment, changing employee duties or engaging subcontractors can create new considerations for workplace injury protection.
Employers should therefore review their arrangements whenever significant operational changes occur.
Regular reviews also provide an opportunity to update employee information, strengthen safety procedures and ensure that internal reporting responsibilities remain clear.
How Mnara Risk and Wealth Advisory Supports Employers in Kenya
Understanding WIBA is an important part of responsible business management, but many employers need assistance navigating the differences between statutory obligations, insurance protection and broader workplace risks.
Mnara Risk and Wealth Advisory helps businesses assess relevant insurance needs and understand the protection options available for their operations.
Our business advisory areas include WIBA, employer’s liability, public liability, professional indemnity, group medical insurance, group life insurance and other corporate protection solutions.
We focus on helping employers understand the purpose of each type of cover, identify relevant risks and make informed protection decisions.
Our approach is guided by three principles: Understand. Plan. Protect.
Whether you operate a growing company, manage a professional office, oversee a construction project or administer employee benefits, understanding your workplace risk responsibilities is an important starting point.
Learn more about our Business and Corporate Insurance services or contact Mnara Risk and Wealth Advisory for guidance.
Final Thoughts on WIBA Insurance in Kenya
WIBA is an important part of Kenya’s framework for protecting employees affected by qualifying work-related injuries and occupational diseases.
For employers, understanding the Act is not only about responding to accidents. It also involves maintaining appropriate protection arrangements, keeping accurate records, reporting incidents correctly and taking workplace safety seriously.
Businesses of different sizes and across different industries should assess their responsibilities rather than assume that work injury requirements apply only to physically demanding occupations.
When an accident occurs, prompt medical assistance, proper reporting and cooperation with the relevant authorities are essential.
Employers who understand their responsibilities are better positioned to manage workplace incidents responsibly and support affected employees through the appropriate processes.
Need guidance on WIBA and workplace insurance protection in Kenya? Speak with Mnara Risk and Wealth Advisory to discuss your business insurance needs.
Frequently Asked Questions About WIBA Insurance in Kenya
1. What does WIBA stand for in Kenya?
WIBA stands for the Work Injury Benefits Act, 2007. It establishes a legal framework for compensation relating to qualifying work-related injuries and occupational diseases.
2. Is WIBA insurance mandatory for employers in Kenya?
Section 7 of the Work Injury Benefits Act establishes an employer insurance obligation concerning liability under the Act. Employers should verify their current statutory responsibilities and maintain appropriate arrangements.
3. Does WIBA apply to small businesses?
Yes. Small business size alone does not create a general exemption from WIBA responsibilities. The applicable employment relationships and statutory definitions are important.
4. Does WIBA cover casual workers in Kenya?
Casual or temporary workers may fall within the scope of WIBA depending on the legal definition of employee and the circumstances of their engagement. Employers should not assume that temporary status automatically excludes a worker.
5. Does WIBA cover domestic workers?
Domestic employment can fall within the scope of WIBA. Households employing workers should review their obligations under the Act.
6. Does WIBA cover office employees?
Yes. WIBA is not limited to industrial or construction workplaces. Qualifying employment-related injuries involving office workers may fall within the statutory framework.
7. Does WIBA cover occupational diseases?
Yes. The Act includes provisions relating to occupational diseases, subject to the relevant definitions, evidence and statutory requirements.
8. How quickly should an employer report a workplace accident?
Official DOSHS guidance requires fatal workplace accidents to be reported within 24 hours and non-fatal accidents within seven days, together with the applicable prescribed reporting procedures.
9. What is the DOSHS 1 form?
DOSHS 1 is the prescribed accident reporting form used in the relevant occupational accident notification process in Kenya.
10. Can an employee report an accident if the employer fails to do so?
Yes. The Work Injury Benefits Act contains provisions allowing an employee to report an occupational accident or disease to the Director. This does not remove the employer’s own reporting responsibilities.
11. Is WIBA the same as medical insurance?
No. WIBA concerns statutory compensation for qualifying employment-related injuries and occupational diseases. Medical insurance provides healthcare benefits according to the relevant insurance contract.
12. Is WIBA the same as employer’s liability insurance?
No. WIBA concerns a statutory compensation framework, while employer’s liability insurance addresses specified legal liabilities under its policy terms. Businesses should understand how their arrangements interact.
13. Does WIBA cover injuries outside the workplace?
Coverage depends on whether the incident meets the legal requirements for an injury arising out of and in the course of employment. The physical location alone does not determine every case.
14. Does WIBA cover employees travelling to work?
The circumstances of travel matter. The Act contains provisions relevant to certain employer-provided transport arrangements, but ordinary commuting should not automatically be assumed to qualify.
15. What happens when an employee dies in a workplace accident?
A qualifying fatal workplace accident may give rise to compensation for eligible dependants under the Act. Employers must also follow the applicable fatal accident reporting requirements.
16. Can an employer ignore an accident because the injury appears minor?
No employer should disregard an injury report merely because it initially appears minor. The relevant reporting requirements and circumstances should be assessed, and appropriate medical attention provided.
17. Does WIBA replace workplace safety requirements?
No. Employers must continue to comply with applicable occupational safety and health obligations. Insurance does not replace accident prevention, training or workplace hazard management.
18. Who investigates workplace accidents in Kenya?
The Directorate of Occupational Safety and Health Services has responsibilities concerning occupational accident investigations and WIBA processing under the applicable framework.
19. What should an employer do immediately after a workplace injury?
Prioritise medical assistance and safety, notify the responsible personnel, document the incident, follow DOSHS reporting requirements and notify the relevant insurer where applicable.
20. Where can businesses get guidance on WIBA insurance in Kenya?
Employers can consult official DOSHS resources for statutory procedures and seek insurance guidance through Mnara Risk and Wealth Advisory when reviewing their business protection needs.